The Global
Industrial Vehicle Market is undergoing significant transformation as businesses increasingly require reliable, high-performance, and digitally connected material-handling equipment across manufacturing, warehousing, freight and
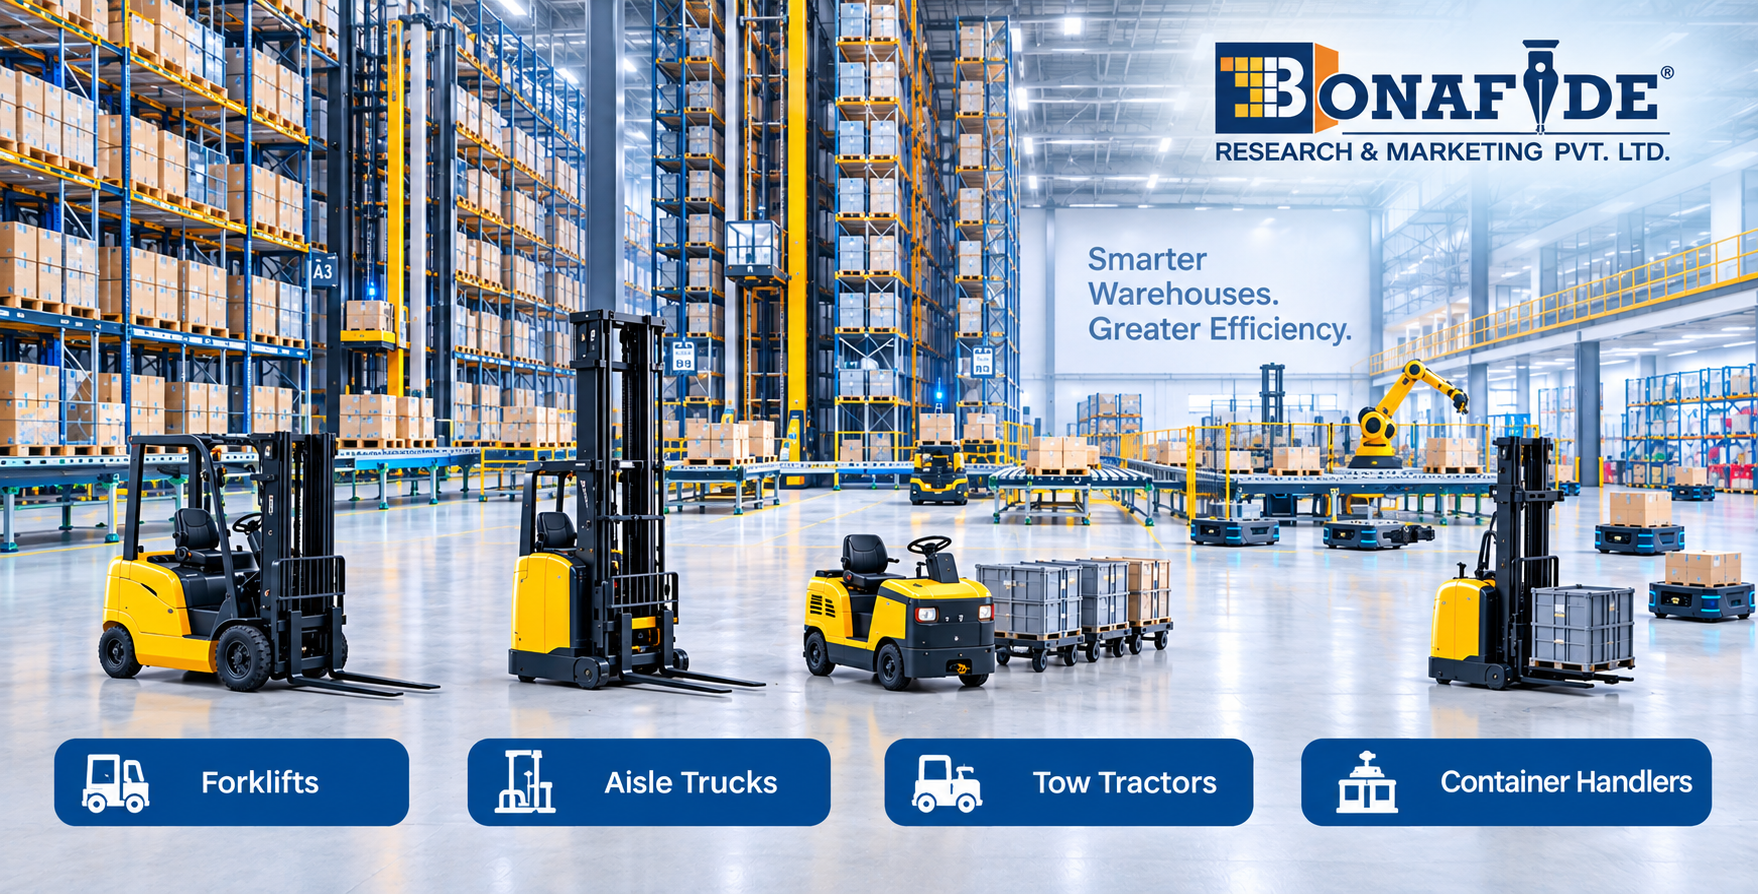
logistics, construction, and mining. Industrial vehicles play a critical role in providing efficient goods movement, inventory management, order fulfillment, and heavy-lift capabilities, enabling operators to achieve improved productivity, reduced emissions, regulatory compliance, and greater operational reliability. The market includes forklifts, aisle trucks, tows tractors, container handlers, personnel carriers, along with electric
propulsion systems, internal combustion engines, hybrid drivetrains, hydrogen fuel cells, telematics,
fleet management software, and associated components. Demand is evolving beyond conventional diesel and gas-powered designs toward electric and hybrid propulsion, smart vehicles with integrated sensors, low-emission configurations, high-efficiency powertrains, sustainable materials, and digitally connected fleet management systems. Manufacturers are increasingly focusing on higher performance, improved energy efficiency, automation compatibility, intelligent controls, real-time monitoring,
predictive maintenance, and smart warehouse connectivity to improve operational experience and reduce total cost of ownership. Forklifts represent the largest vehicle type category because of their proven reliability, versatility, lifting capability, and suitability for a broad range of applications from warehousing to manufacturing. Automated guided vehicles are becoming increasingly important as operators seek labor-independent, high-throughput, and safe material-handling solutions in demanding environments. Aisle trucks are gaining attention across narrow-aisle warehousing due to their space efficiency and high-density storage capabilities. Tow tractors and container handlers are emerging as major growth opportunities in freight and logistics, particularly for horizontal transport and port operations. Smart industrial vehicles with integrated sensors and
wireless connectivity enable real-time condition monitoring; performance tracking, remote diagnostics, predictive maintenance, and automated documentation, helping operators improve
asset management and reduce unplanned downtime. The market is also being transformed by increasing emphasis on environmental compliance and emission reduction. Electric and hybrid propulsion, advanced
battery systems, and sustainable materials are increasingly being incorporated into industrial vehicle specifications. These technologies reduce fuel consumption, support regulatory compliance, and improve operational efficiency across critical material-handling applications.
According to the research report, "Global Industrial Vehicle Market Outlook, 2031," published by Bonafide Research, the global industrial vehicle market was valued at more than USD 48.04 Billion in 2025 and is anticipated to grow at more than 5.28% CAGR from 2026 to 2031. Market estimates can vary depending on the definition of industrial vehicles, product categories included, geographic coverage, and whether smart vehicle technologies,
digital monitoring systems, accessories, and related services are included in the market value. For this analysis, the market is defined around commercially manufactured vehicles specifically designed for material handling, industrial transport, and related applications. The scope includes forklifts, aisle trucks, tow tractors, container handlers, automated guided vehicles, and personnel carriers, along with electric, internal combustion engine, hybrid, and hydrogen fuel cell propulsion systems, smart vehicle technologies with sensors, low-emission configurations, advanced navigation systems, lightweight
composite materials, digital monitoring systems, and associated accessories. The material scope includes steel,
aluminum, composites, and advanced materials depending on application requirements. This definition provides a focused assessment of vehicles directly associated with industrial material handling while minimizing overlap between vehicle types, monitoring systems, and related components. The competitive landscape includes global OEMs, specialized material-handling manufacturers, smart vehicle technology providers, regional manufacturers, and service companies. Competition is increasingly shifting from basic vehicle pricing toward design excellence,
certification, emissions compliance, smart monitoring capabilities, customization, reliability, technical support, and lifecycle services. Manufacturers are expanding their portfolios across different vehicle types, power sources, and weight ranges to serve customers ranging from small and medium-sized enterprises to large multinational manufacturers and logistics operators.
Warehousing applications provide significant commercial opportunities because industrial vehicles are used for receiving, put-away, picking, packing, and shipping. Manufacturing applications create demand for versatile, well-equipped vehicles for production line support, work in progress movement, and raw material handling. Freight and logistics contribute through cross-docking, container handling, and long-distance transport support. Construction and mining provide a broad and diversified customer base requiring heavy-duty, rough-terrain industrial vehicles. The transition toward electric propulsion, hybrid systems, and smart vehicle technologies is creating additional requirements that favor innovative and environmentally friendly industrial vehicle designs. Manufacturers are increasingly replacing older, less efficient vehicles with modern, high performance alternatives where advanced designs can provide improved productivity, reduced emissions, and enhanced operational reliability. Smart vehicle adoption is also expanding as operators seek to monitor vehicle condition, detect potential issues, and optimize maintenance schedules using a single integrated digital platform. Digitalization is changing industrial vehicle design as manufacturers integrate sensors, wireless connectivity, remote monitoring, data analytics, intelligent diagnostics, and predictive-maintenance technologies. These capabilities can improve safety, reduce downtime, optimize maintenance schedules, increase asset utilization, and support data-driven operations.
Artificial intelligence and software-based condition monitoring are also creating opportunities for automated performance tracking, fault detection, and maintenance optimization. Automation represents another major development area. Manufacturers are increasingly integrating automated systems, digital documentation, remote calibration, and connected monitoring systems. These systems help address labor shortages while improving safety and compliance. Fully integrated smart vehicle systems can connect equipment with warehouse management platforms, supporting the development of smart warehouses and connected logistics operations. Overall, the global industrial vehicle market is positioned for sustained expansion through 2031, supported by the replacement of aging fleets, increasing adoption of electric and smart vehicles, rising demand for sustainable designs, automation and digital integration, warehouse infrastructure expansion, and industrial growth. Electric propulsion, smart vehicles, sustainable materials, and digitally connected equipment are expected to remain the most important areas of market development through the forecast period. These developments are expected to strengthen the strategic importance of industrial vehicles across the global manufacturing, logistics, and supply chain landscape.












 We are friendly and approachable, give us a call.